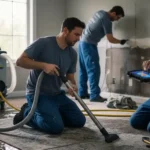
A burst pipe above a finished ceiling, a roof opening after severe weather, or a fire followed by firefighting water can turn one damaged room into several affected spaces. In basement-heavy homes, older housing stock, mixed-use corridors, and commercial properties, damage may cross walls, floors, tenant areas, and mechanical spaces before the full scope is obvious.
That is where an insurance restoration contractor differs from a basic cleanup crew or repair-only contractor. The job is not to decide what your policy covers. The job is to document conditions, limit additional damage, define the restoration scope, and carry the property from emergency work into repair when those services are included.
What an insurance restoration contractor actually handles
A multi-room loss needs connected documentation, mitigation, and repair planning rather than disconnected jobs.
Document the loss before cleanup changes the scene
Good documentation starts with the condition of the property. That can include room photos, closer views of visible damage, affected materials, the apparent source when known, and notes about how water, smoke, soot, or debris traveled.
For a water damage restoration insurance claim, the record should help explain which rooms were affected, what materials were wet, what was removed, and why the scope changed if hidden damage appeared. A related guide on water damage and insurance coverage can help separate restoration decisions from coverage questions.
Mitigate the active damage
Mitigation comes before cosmetic repair. With water loss, that may mean source control, extraction, drying, and removal of affected materials when necessary. With storm damage, temporary protection may be needed if the building envelope is open. With fire damage, the property may also have smoke, soot, odor, debris, and suppression water.
The sequence matters because a freshly painted wall does not solve moisture behind it, and replacing flooring does not solve water trapped below the surface.
Rebuild what mitigation had to open or remove
Once the loss is stabilized, the project shifts from emergency response to restoration and reconstruction. Drywall, trim, flooring, ceilings, and other finishes may need repair or replacement based on the documented condition.
A contractor that performs both phases can carry the original loss record into the rebuild. That continuity helps reduce gaps between what was removed during mitigation and what belongs in the repair scope.
Why multi-room losses create claim and scope problems
The more spaces involved, the easier it is for documentation and repair scope to become fragmented.
Water can follow framing, drop to the level below, move under flooring, or enter adjoining units. Smoke and soot can travel beyond the room where a fire started. In a commercial or multi-unit property, the same event may affect hallways, tenant spaces, storage rooms, or shared building components.
The response should map the whole path of damage rather than treat each stain as an isolated issue. For shared-space water events, see the guide to common-area water losses and shared drying.
Who does what during an insurance-related restoration
Clear roles reduce confusion when the contractor, property owner, insurer, and adjuster are all involved.
Your role as the property owner or manager
- You provide access, share what you know about the event, preserve relevant records, and communicate with your insurer about the claim.
- Keep copies of photos, estimates, authorizations, invoices, and important claim communications.
- For commercial properties, also document operational effects such as closed rooms, tenant access problems, affected inventory areas, or customer-route changes when relevant.
The restoration contractor’s role
The contractor evaluates physical damage, documents affected areas, performs authorized mitigation, records work completed, and prepares the repair scope for the restoration work it will perform.
Insurance water damage restoration help should make the physical side of the claim easier to understand. It should not blur the line between documenting damage and making coverage decisions.
The insurer or adjuster’s role
Coverage, limits, deductibles, and claim payment decisions belong to the insurance side. A restoration contractor can provide photos, scope details, estimates, and project documentation, but should not present itself as the final authority on what your policy will pay.
That distinction matters in both water losses and fire damage claims.
Fire and water losses need different documentation priorities
The core workflow is similar, but the evidence and cleanup questions change by loss type.
Water losses follow the moisture path
A water claim may begin with a frozen pipe, appliance leak, roof leak, heavy rain, basement flooding, or backup. The visible puddle is only one part of the event.
- Documentation should follow the spread into flooring, drywall, ceilings, lower levels, and adjacent rooms.
- Understanding how water damage restoration is performed can also help you see why extraction and repair are separate stages of the same recovery.
Fire losses can include several damage mechanisms
Fire damage claims may involve burned materials, smoke residue, soot, odor, debris, broken openings, and water used during suppression. That creates a broader room-by-room record than the burn area alone.
When you need fire damage insurance claim help, keep the cleanup question separate from the coverage question. The contractor should explain the restoration scope. Your insurer should explain policy coverage. The guide to fire damage cleanup and insurance coverage provides additional context.
How to evaluate the right response after a multi-room loss?
The best response keeps documentation, mitigation, and rebuild scope connected without confusing restoration work with insurance decisions.
Key questions to ask before you move forward
- Will the initial documentation cover every affected room, level, and shared area?
- How will the scope distinguish emergency mitigation from permanent repairs?
- If hidden damage appears, how will it be documented before the scope changes?
- Can the same restoration plan carry from cleanup into reconstruction?
- Who will give you project updates and explain changes in the work?
You should be able to see how the contractor will track the physical loss from first inspection through repair.
What a well-managed recovery usually includes
A strong recovery has a clear sequence and a record that stays understandable as the project changes.
It usually includes an initial damage record, an authorized mitigation scope, notes or photos showing what changed during cleanup, a defined repair scope, and a final review of completed work. The exact steps depend on whether the loss involves water, fire, smoke, sewage, storm exposure, or another source.
Early warning signs of a poor cleanup plan
- Watch for a plan that focuses only on visible surfaces, cannot explain what happens if damage appears in an adjoining room, mixes insurance coverage promises with restoration decisions, or has no clear handoff from mitigation to rebuild.
- Before closing the project, use a final inspection checklist after water damage restoration to review repaired areas, remaining concerns, and documentation.
Frequently Asked Questions
What does an insurance restoration contractor do after a multi-room loss?
An insurance restoration contractor addresses the physical property damage and documents the restoration work. The scope may include emergency mitigation, cleanup, drying, removal of damaged materials, repairs, and reconstruction. Insurance coverage decisions remain separate from the contractor’s restoration responsibilities.
Who should document damage before cleanup begins?
- You should preserve photos and other records when conditions are safe, and the restoration contractor should document the affected areas as part of the project record.
- Documentation is especially important when damage crosses several rooms or floors.
- Avoid entering areas with electrical, structural, fire, sewage, or other obvious hazards simply to take pictures.
Is a restoration contractor the same as an insurance adjuster?
No. A restoration contractor assesses and repairs physical property damage. An insurance adjuster evaluates the claim from the insurance side, including applicable policy provisions, limits, deductibles, and settlement calculations. Keeping those roles clear helps prevent misunderstandings during recovery.
Why is documentation harder after a multi-room water loss?
Water does not necessarily remain in the room where the leak started. It can move beneath flooring, through wall assemblies, into ceilings below, or toward adjoining rooms. A useful restoration record therefore follows the path of the loss instead of documenting only the most visibly wet area.
What documentation helps with a water damage restoration insurance claim?
- Useful records can include photographs, videos, damaged-property lists, contractor estimates, invoices, and information showing where damage occurred.
- Keeping records organized by room can make a larger loss easier to understand.
- Your insurer can tell you which specific claim documents it needs.
How are fire damage claims different from water claims?
A fire loss can involve several forms of damage at once, including burned materials, soot, smoke residue, odor, debris, structural damage, and water from suppression efforts. That means documentation should extend beyond the visibly burned area. Repair decisions should follow the actual documented conditions throughout the property.
Can the restoration contractor tell me whether insurance will cover the work?
The contractor can explain the physical restoration scope, provide estimates, and document the work performed. Your insurer or insurance representative should answer questions about policy coverage, deductibles, limits, and claim payment. Do not treat a contractor’s restoration estimate as a coverage determination.
What happens if hidden damage appears during mitigation?
Hidden damage may become visible when wet or damaged materials are opened or removed. The new condition should be documented clearly so the repair scope can reflect what was actually found. If an insurance claim is involved, keep the insurer informed about material changes to the documented loss.
Can one contractor perform both mitigation and reconstruction?
Yes, when both services are within that contractor’s scope. A connected workflow can preserve continuity between what was removed during mitigation and what later needs repair. We provide restoration services that include emergency restoration work and property reconstruction for applicable loss types.
What should property managers watch for after damage crosses tenant spaces?
- Start by identifying every affected tenant area, common space, access route, storage area, and building component that may be involved.
- Keep documentation organized by space and record changes as the scope develops.
- A coordinated plan can reduce confusion when several occupants and decision-makers are involved.
What should I ask before hiring an insurance restoration contractor?
- Ask how damage will be documented, who manages project communication, how emergency work is separated from permanent repairs, and how newly discovered damage is recorded.
- Also ask whether the contractor can perform the rebuild or whether another handoff will be required.
- The answers should give you a clear picture of the recovery workflow.
Related posts:
![5.-What-is-included-in-restoration]()
What’s Included in Restoration? A Complete Guide for Property Owners
![What Shared Buildings Should Inspect Before Summer Programs]()
What Shared Buildings Should Inspect Before Summer Programs
![Learn All About Our Deep Cleaning, Coronavirus Services]()
Learn All About Our Deep Cleaning, Coronavirus Services
![3 Measures To Protect Your Property From Flooding]()
3 Measures To Protect Your Property From Flooding
![Storm Damage Restoration Why Flat Roof Leaks Show Up Late]()
Storm Damage Restoration: Why Flat Roof Leaks Show Up Late
![Vehicle Impact Damage: Why Repairs Cannot Come First]()
Vehicle Impact Damage: Why Repairs Cannot Come First
![Ice Maker Leak Water Damage Assessment Guide]()
Ice-Maker Leak Water Damage Assessment Guide