
Homeowners insurance may cover some mold-related costs, but the answer depends on the policy and the circumstances that produced the growth. The source of moisture, timing, exclusions, endorsements, and limits can all affect the decision. A contractor cannot determine your coverage from a photograph.
For Wisconsin homeowners, the practical approach is to document the condition, address safety and ongoing moisture, and ask the insurer how the actual policy applies. Do not assume that coverage for an initial water incident automatically includes every later mold expense.
Begin with the cause rather than the cleanup label
Different water events can have different coverage
A sudden plumbing incident, prolonged seepage, sewer backup, and ground flooding are not interchangeable insurance situations. The Wisconsin insurance regulator's water-damage guidance explains important distinctions between sources and separate coverages.
Describe what happened accurately. Do not relabel a recurring leak as sudden simply because growth was discovered recently. The discovery date and the start of the underlying moisture problem can be different facts.
Mold provisions may differ from the water coverage
Ask whether the policy includes a mold exclusion, a specific limit, or an endorsement that changes the terms. Also ask whether testing, access, removal, drying, and rebuilding are evaluated separately.
The policy's language matters more than a general online statement that mold is always covered or never covered. Request a written explanation when the insurer approves, limits, or denies a particular expense.
Create a clear record of the property condition
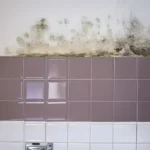
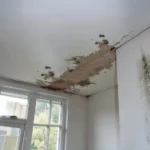
Photograph accessible growth and surrounding damage without disturbing suspect materials. Save leak-repair findings and note when stains, dampness, or odors first appeared. If earlier work occurred, keep those records as well.
- Record discovery dates and affected rooms.
- Save source-repair invoices and photographs.
- Keep cleanup estimates broken into defined tasks.
- Note any previous moisture incidents accurately.
- Retain correspondence and claim reference numbers.
If unsafe conditions or active moisture need attention, do not delay necessary protective measures solely to create a perfect claim file. Notify the insurer promptly and ask what documentation is required before nonurgent disposal or permanent repairs.
Request a remediation scope the insurer can evaluate
Define the affected materials and proposed decisions
An estimate should identify the work area, source concerns, material retention or removal, and any access needs. A single line labeled mold treatment does not explain what the provider will do or why.
Discuss mold removal services with Emergency Restoration Specialists at (414) 571-9977. Ask for a property-based scope while keeping payment questions with the insurer.
Separate cleanup from optional improvements
Necessary remediation and source repair may differ from broader upgrades. Clarify whether a ventilation improvement, remodeling choice, or replacement with upgraded finishes is included in the claim decision.
|
Expense category |
Coverage question to ask |
|
Mold assessment |
Is this task included under the policy's applicable terms? |
|
Affected material removal |
What findings support the proposed scope? |
|
Source repair |
Is the defective component covered or only resulting damage? |
|
Drying and cleanup |
Does a limit or exclusion apply? |
|
Rebuilding |
What finish restoration is included? |
|
Optional improvements |
Which costs are the homeowner's responsibility? |
Avoid turning a claim dispute into a delay in moisture work
Property recommendations and coverage decisions have different roles
A remediation provider explains what the condition calls for. The insurer evaluates payment under the contract. A recommended task can be technically appropriate without being covered, and an approved amount does not by itself establish the complete scope.
Ask what requires prompt action, what can wait, and how new findings will be recorded. Agree on change procedures before concealed areas are opened so additional work is not treated as an undocumented surprise.
Keep consumer resources available for unresolved questions
The Wisconsin guide to settling property claims provides information for policyholders and directs unresolved complaints to OCI after discussion with the insurer. It does not replace legal advice about a specific dispute.
- Request the policy language behind decisions.
- Ask about deductibles and special limits.
- Keep estimates and invoices distinct.
- Document why protective work was needed.
- Follow up in writing on unresolved scope questions.
Confirm moisture correction regardless of the payment outcome
The EPA's mold guidance emphasizes addressing growth and the moisture supporting it. An insurance outcome does not change the need to investigate a leak or recurring dampness.
The ERS team can discuss the restoration side of the property concern. Call (414) 571-9977 to review affected materials, and ask your insurer directly about coverage before relying on any promise of reimbursement.
Frequently Asked Questions
Is mold always excluded from homeowners insurance?
Not under every policy and circumstance. Specific wording, endorsements, cause, and limits matter, so ask the insurer to explain the relevant provisions rather than rely on a universal rule.
Does covered water damage guarantee mold coverage?
No. Mold-related costs may have separate conditions or limits. Ask how the policy applies to the growth and proposed remediation in addition to the original water incident.
Can a restoration company approve the claim?
No. A provider can explain and document its work, while the insurer evaluates payment under the policy. Treat contractor statements about coverage as questions to verify.
Should I document old leaks too?
Yes, share relevant history accurately. A new discovery date does not prove the moisture began that day, and prior records can help explain the condition.
Is mold testing always reimbursed?
No universal answer applies. Ask whether testing is necessary for the scope and whether the applicable policy terms include that expense before assuming reimbursement.
What if the estimate changes after opening a wall?
New findings can affect the scope. Ask how photographs, material observations, and approvals will be recorded before additional work proceeds.
Will a prevention upgrade be paid for?
Not necessarily. Optional improvements may be treated differently from restoring covered damage. Separate those costs so the coverage discussion is clear.
Should I delay cleanup until the insurer responds?
Do not ignore safety or ongoing moisture. Notify the insurer promptly, document conditions, and ask about required inspection before nonurgent disposal and permanent repairs.
Where can Wisconsin homeowners raise unresolved insurance concerns?
Begin with the insurer or agent and request a written explanation. Wisconsin OCI provides consumer guidance and complaint channels when satisfactory answers remain unavailable.
Does claim denial mean remediation is unnecessary?
No. Coverage and property condition are different questions. A denied expense does not establish that growth, wet materials, or a moisture source can safely be ignored.
Related posts:
![Where Does Mold Grow?]()
Where Does Mold Grow?
![How to Remove Mold From Your House: What's DIY and What Isn't]()
How to Remove Mold From Your House: What's DIY and What Isn't
![Why-Milwaukee-Homes-Are-Prone-to-Mold-Growth]()
Why Milwaukee Homes Are Prone to Mold Growth
![Damage Inspection: The Process]()
Damage Inspection: The Process
![mold-after-water-damage-what-you-need-to-know-and-how-to-act-fast]()
Mold After Water Damage: What You Need to Know and How to Act Fast
![Tips-for-Handling-Mold-and-Water-Damage-in-a-Rental-Property-300x200-1]()
Tips for Handling Mold and Water Damage in a Rental Property
![9.-4-Health-Effects-of-Mold-From-Water-Damage]()
4 Health Effects of Mold From Water Damage